Special Audit

Architectural details in stone and glass

Independent Assessment of Adopted Financial Statements

A special audit is a distinct procedure governed by the Slovenian Companies Act (ZGD-1), designed to verify specific statements or notes in the financial statements that form an integral part of the adopted annual report. The appointment of a special auditor is decided by the court under statutory conditions. At AUDITING, we tailor our approach to the scope of the court order, the company’s circumstances, and the requirements of applicable professional standards.
When Can a Special Audit Be Requested?

Pursuant to Article 322 of the ZGD-1, the court may appoint a special auditor if there is reason to believe that certain line items in the financial statements are substantially understated, or that mandatory notes in the disclosures are deficient, and management failed to provide them at the general meeting despite shareholder requests and a formal request to enter the questions into the minutes. A motion may be filed by shareholders representing at least one-tenth of the share capital or holding shares with a nominal or proportional value of at least EUR 400,000. Compliance with other statutory requirements is assessed on a case-by-case basis.
Light and refraction of a beam through a glass prism
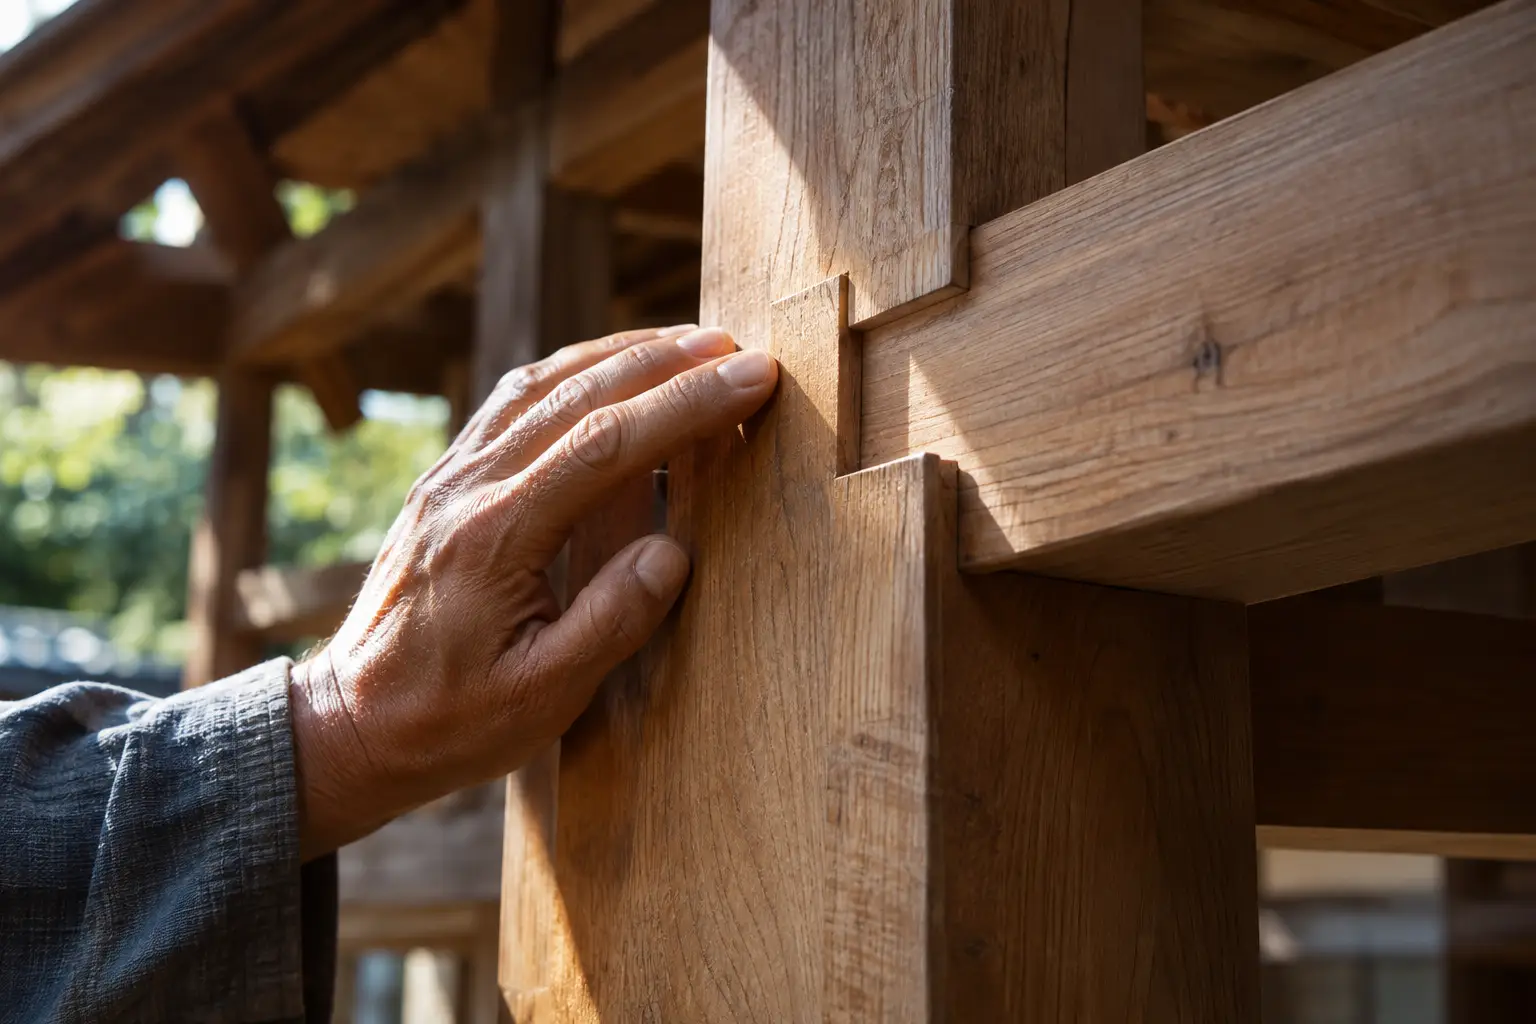
Close-up examination of a crafted wood joint

Report on the Findings of the Audit

During the audit, we evaluate the valuation of the items under review and the adequacy of the disclosures within the defined scope of engagement. In doing so, we adhere to statutory provisions, accounting standards, and the principles and assumptions governing the preparation of financial statements. The special auditor prepares a written report on the outcome and submits it to company management and the court in accordance with the provisions of the ZGD-1.